
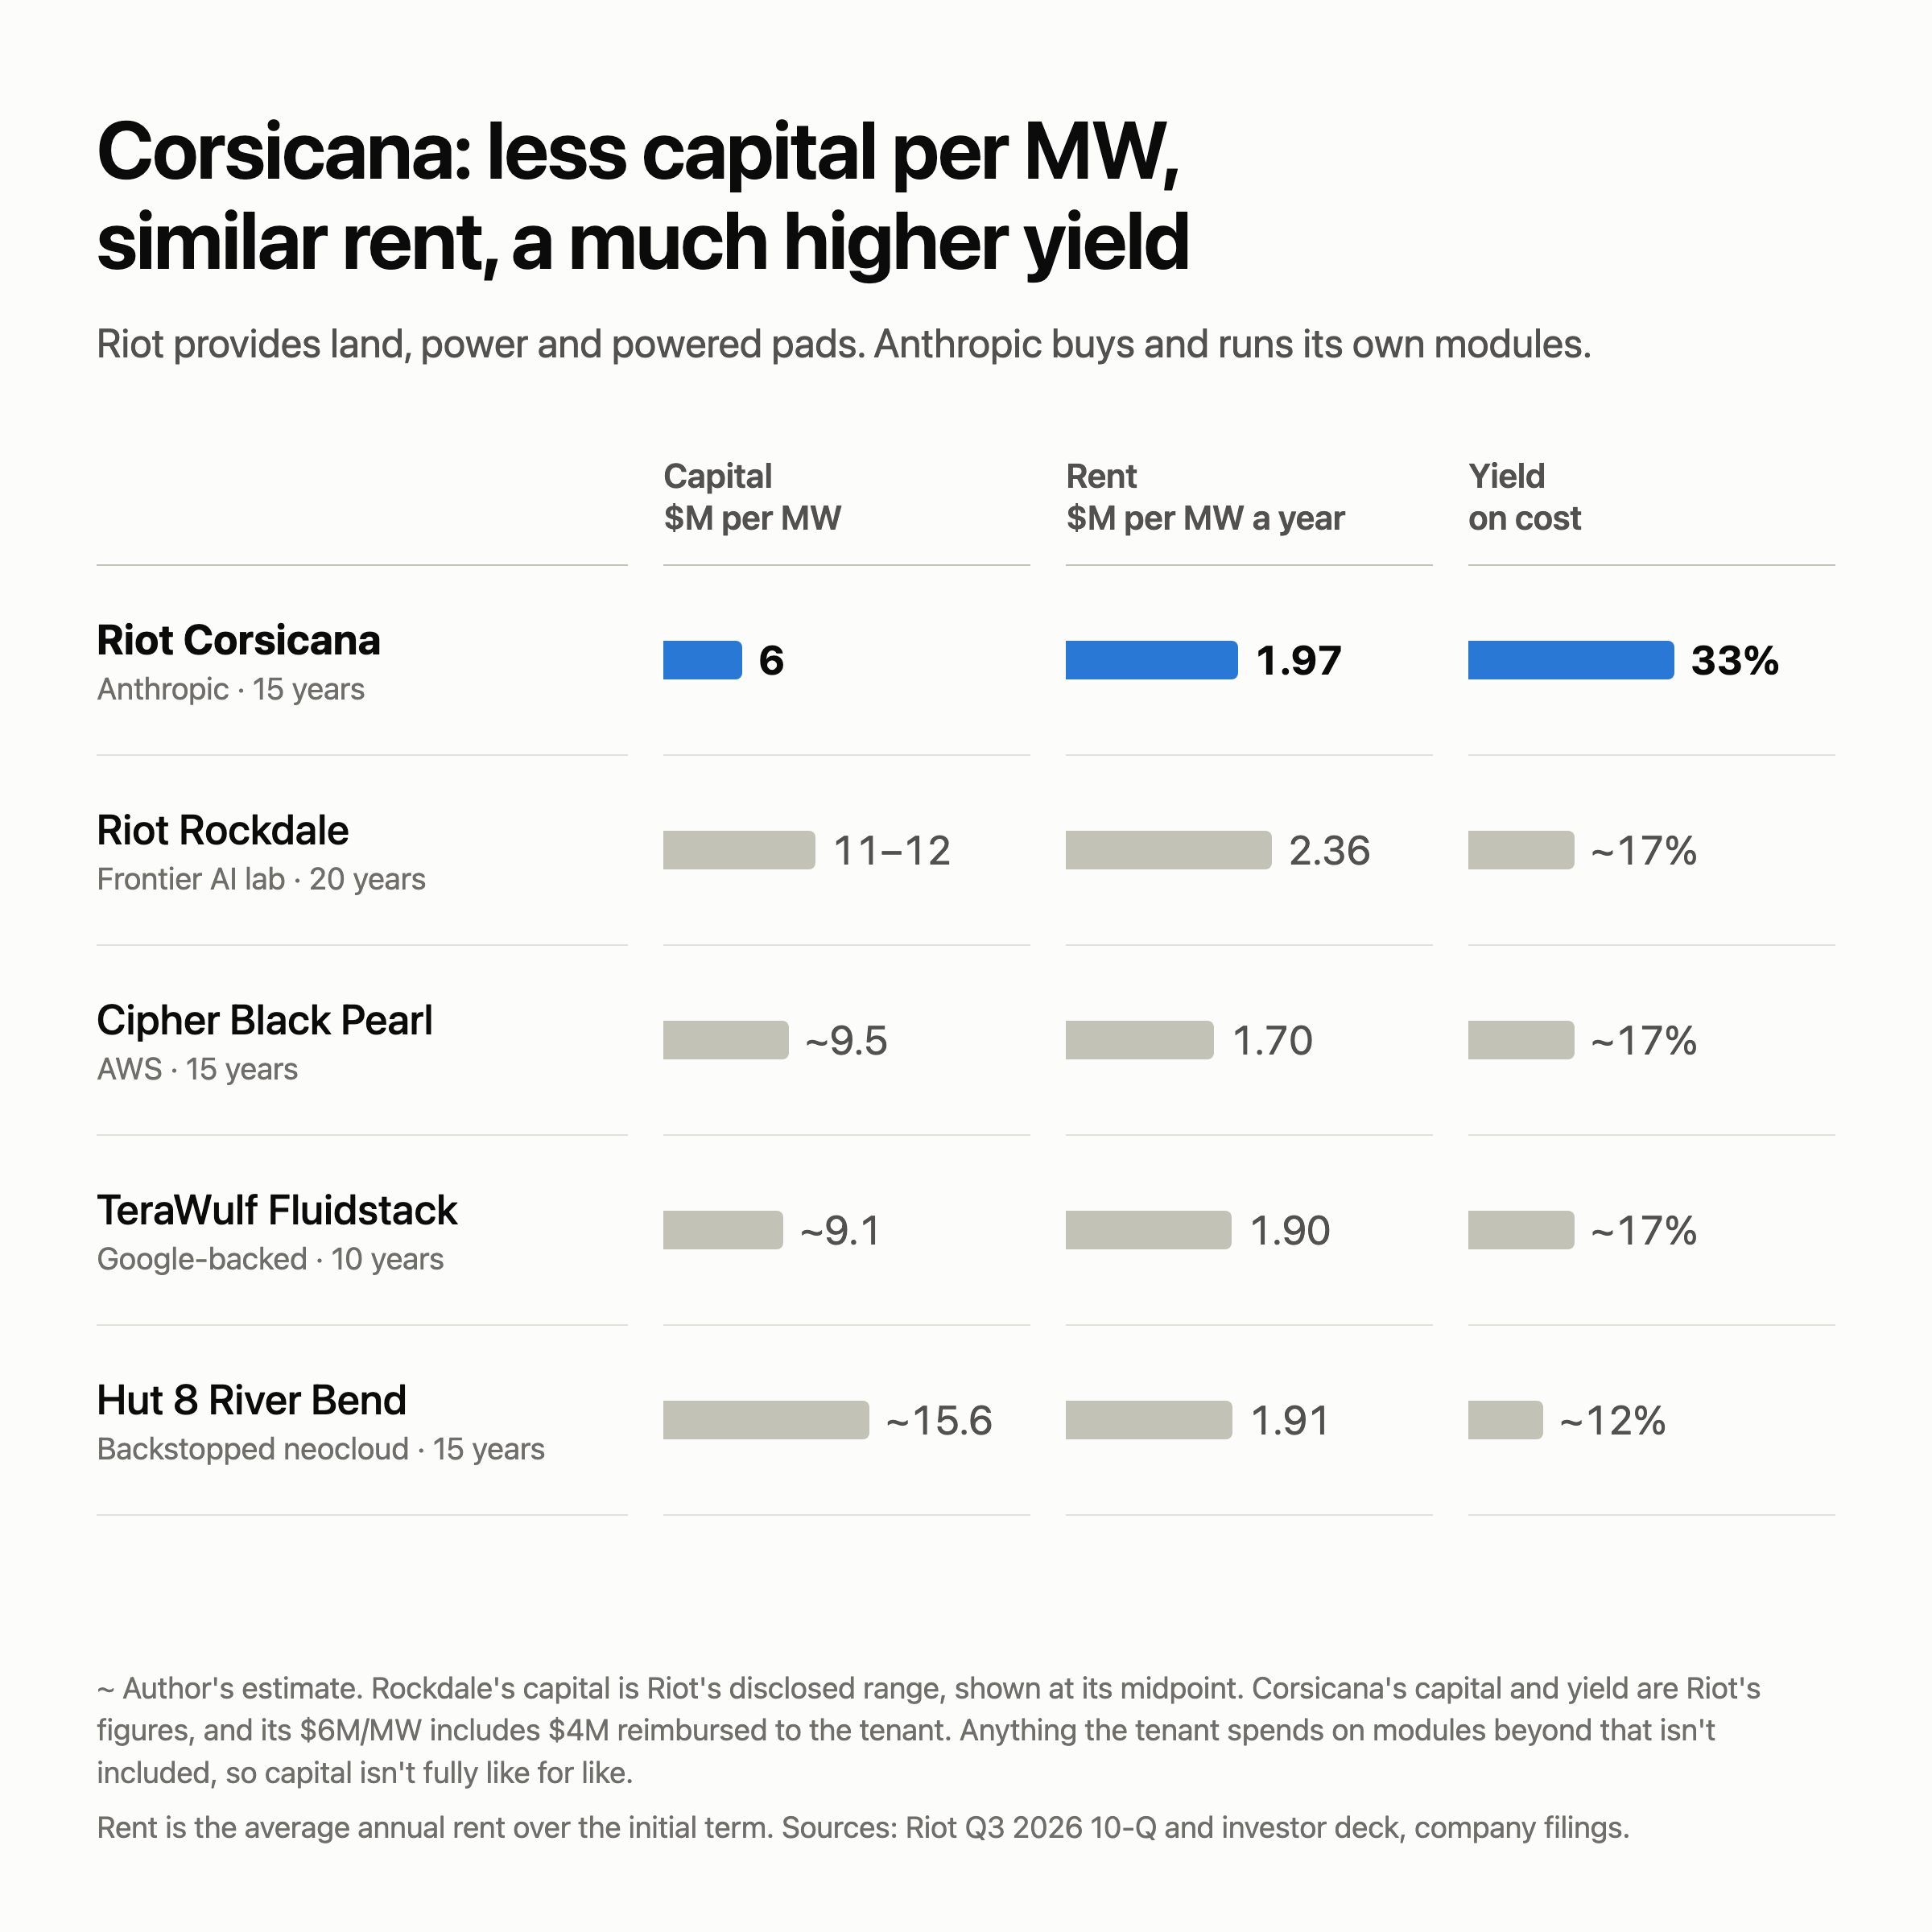
Riot has signed a 15-year lease worth about $28B for 910 MW at Corsicana, Texas. The press release calls the tenant a "Frontier AI Lab." The 10-Q says it's Anthropic.
The unusual part is how little Riot builds. It provides the land, power and powered pads, while Anthropic buys, installs, owns and runs the modules. Riot puts the cost at $6M/MW, against roughly $9-16M on comparable leases by my estimates. Rent doesn't fall with it: at an average of $1.97M/MW a year, it's toward the high end of those leases. That's how Riot gets to a 99% NOI margin and a 33% yield on cost. I get 12-17% on the comparables.
I'd adjust those numbers a little. The 33% uses average rent over the lease. Rent starts at $130/kW/month, or about $1.42B a year at full capacity, and rises 3% a year, so the yield on starting rent is closer to 26%. That's still very high. The $1.8B of average rent and the 99% margin also exclude the amortization of up to $3.6B in reimbursements to Anthropic. I estimate that will take about $240M a year off reported revenue, though it doesn't change cash rent.
Those reimbursements matter more for the financing. Of the $6M/MW, $4M goes back to Anthropic for modules Anthropic owns. Anyone lending against this project is mostly underwriting Anthropic's rent, with far less in physical assets behind the loan.
Riot does have a fallback. The plan is $4.4-4.9B of non-recourse project debt, plus $0.5-1.1B of Riot's cash. If debt isn't available on comparable terms, Anthropic funds the reimbursements itself and recovers them through rent credits at 12%, though Riot still has to pay for $1.8B of site work. I estimate Riot would keep about $750-900M a year at full capacity on starting rent in either case. That assumes 7-10% debt over 15 years in the first case, and no debt on the site work in the second.
On paper, these are the best economics in the sector. I wouldn't call it the safest deal. Part of that yield pays for scarce power and fast delivery, and part of it pays for credit risk. Riot describes investment-grade support at Rockdale but doesn't describe any at Corsicana. Press reports say Rockdale's tenant is also Anthropic, which would make one customer 96% of Riot's leased MW. If the tenant failed, Riot would still have the land and 1 GW of connected power, and that's a valuable thing to be left with.
The first real test is the debt raise in 2027. A fallback to rent credits would say a lot about how lenders see Anthropic's credit. After that comes delivery of the first block, targeted for June 28, 2027. Texas is the other open question: Riot says it needs no further approvals, but the governor-elect has promised a moratorium.
Personal analysis, not investment advice.